
passive
What is a liability?
In accounting, the liability represents all obligations that a natural or legal person must fulfill in the future, because they are the result of financial transactions that occurred in the past. They usually consist of debts, payments to suppliers, salaries, etc.
The liabilities of an organization, along with the net worth, is the way in which an organization or company finances its assets. Thus, it plays a fundamental role in a company, since it is one of the elements that make up the basic accounting equation of the balance sheet.
Classification of liabilities
According to its components and the most commonly used classification, there are 2 types of liabilities: current and non-current liabilities.
Current liabilities
Current liabilities, also known as current liabilities, are represented by those liabilities that must be completed in a period of less than one year.
Among the most common current liabilities we can find salaries, taxes, electricity expenses, etc.
Non-current liabilities
Non-current liabilities, also known as fixed liabilities, are made up of those liabilities that must be completed within a period of more than one year.
Among non-current liabilities we find long-term loans, mortgages, among others.
How is the liability of an organization calculated?
One of the ways of knowing the liabilities of an organization consists of consult the financial statements of it, more precisely the balance sheet.
If the balance sheet is not known, it will be necessary add the nominal value of each of the obligations or payments that must be fulfilled in the future.
If we know the organization's net worth and the assets it owns, we can make use of the basic accounting equation to calculate the liability. That is:
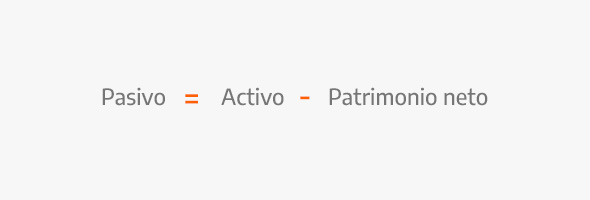
Basic accounting equation to calculate the liability.
When a liability increases on the balance sheet, at the same time there is an increase in assets, since the possession of an obligation or debt supposes, at the same time, the obtaining of a good or right.
Examples of liabilities
To better understand this concept, let's look at some examples of liabilities that are usually found in accounting:
| Current liabilities | Non-current liabilities |
|---|---|
| Salaries to pay. | Mortgage loans. |
| Rentals. | Long-term credit. |
| Short-term credit. | Bonds or obligations payable. |
| Debts with suppliers. | Long term debts. |
| Taxes to be paid. |
Leave a Reply