
Specific asset
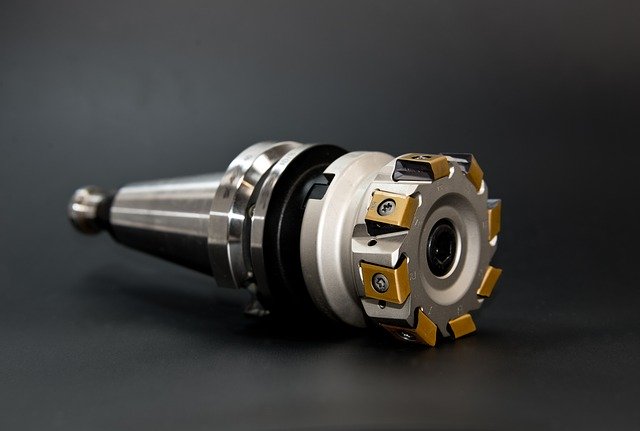
A specific asset is one whose owner cannot be separated without costs or losses. In other words, these are goods that are difficult to adapt to other processes or areas.
Seen in another way, a specific asset is one that was acquired or developed by a company for a specific purpose. Thus, it cannot be adapted without additional cost to another activity.
It should be clarified that assets can have different degrees of specificity. Thus, the less adaptable the good is, the more it will depend on the objective for which it has been constituted.
Specific assets and opportunism
When a company or person owns a specific asset, it runs the risk of being a victim of the opportunism of another agent, who will try to maximize its profit.
This can happen, for example, if a home is installed to use natural gas instead of liquefied petroleum gas (LPG). Then, an initial investment has been made that will be paid in monthly installments.
Initially, the monthly variable cost is significantly lower with the new system than with LPG. However, the distribution company decides after one year to increase the cost per cubic meter of natural gas consumed.
In this case, the consumer has no choice but to accept the new transaction conditions.
Fixed assets and transaction costs
The economist Oliver E. Williamson warned about the possibility of opportunistic actions like the one we have explained above.
This can be understood by the fact that markets do not function in perfect competition, but with asymmetric information and uncertainty. This, in turn, is part of the foundation of the transaction cost theory.
It should also be noted that the presence of asymmetric information forces companies to contract guarantees, for example, when they are going to buy an asset, especially if it is specific. In this way, the firm can file a claim if the purchased product does not meet expectations.
Leave a Reply