
Redeemable
The term amortizable, from a financial point of view, refers to a business loan that is repaid in periodic payments and is used for investment. From an economic point of view it defines those assets that depreciate over time.
Therefore, this expression is related to two very different aspects. On the one hand, with financing, in a way that expresses the way we pay it, including capital and interest. On the other, with investment, in relation to an asset that depreciates and loses value over time. In this way, the company must record both facts in its accounting.
Amortizable and depreciable amount
If we focus on assets, the depreciable amount is always calculated on the acquisition price minus the residual value, if any. The latter would be the market value at which said good would be expected to be sold in the future. It must be borne in mind that the objective is to sell it when it has exceeded its useful life and, therefore, is amortized.
This concept is similar to the depreciable amount, since the asset is amortized, precisely because it is depreciated. In this way, this loss of value is calculated by dividing the net book value (NCV) of the asset by its useful life. In turn, this NCV is calculated as the acquisition price reduced by the accumulated depreciation of other years.
In the financial aspect, there is a term that is "non-amortizable" and refers to the issued obligations that do not allow early amortization (sale). Therefore, you have to wait for the expiration date to sell them.
Examples of amortizable
Here are some concrete examples to clarify the above concepts:
- If our company requests a loan to buy a machine, it can choose to return it based on the useful life of said good and with periodic installments, as in a French loan. This would be a case of a repayable loan.
- Our company requests a loan, but this time it prefers to repay it in a single payment, as in an American loan, at the end of the period. It would be another type of repayable loan similar to the previous one.
- The company purchases a series of computer equipment for an amount of 12,000 currency units (CU) and with a residual value of CU2,000. Its useful life is 5 years. This would be the case of a depreciable asset and the annual fee for this depreciation could be calculated as follows:
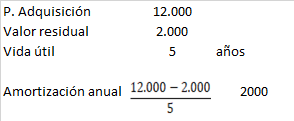
Leave a Reply