
Realizable asset
The realizable asset is that set of assets that tends to become an asset available to the company in the short term.
In other words, it is an accounting label between the time of sale and the time of collection:

Then, it consists of the intermediate process from when we have the stocks in our possession in order to put them up for sale, until the client pays us for that sale and the amount reaches our treasury.
Characteristics of the realizable asset
This asset differs to a large extent from other assets, such as fixed assets or the treasury itself. Some of the characteristics that make the realizable asset a 'free verse' at the accounting level are:
- Intangibility: This asset is intangible, since we cannot express it physically. However, we can prepare an invoice or similar debt acknowledgment document that details how much is owed to us.
- Current: The short-term nature of the asset makes us think that its payment will be imminent.
- Financial: Since most of these assets are debts in our favor with clients, debtors or others, their deferral and subsequent payment indicates that it is a financial way to face future payments.
- Deferred: This is an accounting item that shows a value that we are supposed to receive after making a sale. This means that until we charge for the good or the service performed, we will not be able to count on the amount to be collected.
Therefore, the realizable asset will be intangible, current, financial and deferred. Except, yes, in a case that skips any of the previous characteristics.
Example of a realizable asset accounting entry
An accounting example in which we could classify the asset generated in our accounting as a realizable asset could be the following:

In this case, the 'clients' account is the one that is categorized as a realizable asset. Which will vanish from our accounting when we collect the debt created with the previous entry.
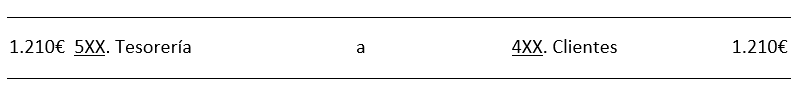
As we can see, the realizable asset totally disappears giving rise to the collection of the debt in our treasury. This entry can only be made when we have actually collected the item due to the accounting principle of prudence.
Leave a Reply