
Book depreciation per unit produced
The method of accounting depreciation per unit produced is a way of calculating the loss of value of an asset by estimating the units produced annually and not based on the duration of its useful life. In the NIF it appears as the method of production units. It is also known as activity-based amortization..
This is a method adapted to a specific production whose use must be previously approved by the Tax Agency in order to be considered a deductible expense.
Calculation of the repayment installment
To know what is the annual expense for the depreciation of the assets, the company must establish a production plan that considers the total production during the period of use of the asset and the units to be produced each year:
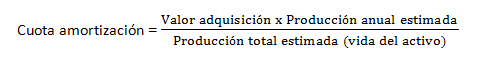
Example accounting depreciation per unit produced
A company acquires a machinery on 01/01 / 20XX for an amount of 20,000 euros. The company interprets that the best amortization method to apply is the amortization method per unit produced. Thus, it establishes a production plan for a useful life of 4 years that is approved by the country's regulations. This is the plan:
1st year: 1,000 units
2nd year: 2,000 units
3rd year: 2,000 units
4th year: 3,000 units
TOTAL UNITS = 8,000 units
What is the annual amortization expense?
1st year) Amortization = (20,000 * 1,000) / (8,000) = € 2,500 / year
2nd year) Amortization = (20,000 * 2,000) / (8,000) = € 5,000 / year
3rd year) Amortization = (20,000 * 2,000) / (8,000) = € 5,000 / year
4th year) Amortization = (20,000 * 3,000) / (8,000) = € 7,500 / year
Accumulated amortization year 4 = 20,000
Net book value of the machine = (Purchase price - Accumulated depreciation) = 0
Leave a Reply