
Accounting note
An accounting entry is that entry that will detail any commercial or economic movement that modifies the assets of a person or company.
In accounting, accounting notes are used to record each of the operations carried out by a company. Each accounting entry assumes an accounting record in the journal, and then a record in the general ledger.
We will find an accounting entry in the accounting book normally made up of:
- The date
- The accounting account
- The amount
- A little description
We will also identify it by the following words: Debt and Credit, there will be an entry in the Debt (income or debit) and another entry in the Credit (payments or credits), which generally affect the liabilities and assets through a counterpart.
We can find the accounting entries in entries of:
- Simple game: We reflect the movement through a single point.
- Double match: The movement influences at least two different accounts, so it will be an accounting entry with two accounting entries.
To understand double entry accounting entries we could think of the following idea: There is no origin without destination, nor destination without origin.
What is an accounting entry for?
It is an instrument of classification and accounting organization, since it allows us to know at any time each one of the movements made, where they come from and where both assets and liabilities go.
Example of an accounting entry
Let's imagine that we run Adagio SL a piano shop.
We make a purchase of € 1,000 worth of merchandise, in our case pianos, which we will pay in cash to our supplier. When it comes to a company, this simple operation that our head performs automatically, needs to be recorded.
Any movement that occurs will affect two different accounts, on which we will have to record an accounting entry. In the case at hand, we will have to withdraw € 1,000 from cash (plus VAT) to deliver them in exchange for our merchandise. Therefore, we will have to make an accounting entry in the Cash account and another in the Merchandise Purchase account. In this case, as we also have to pay VAT, we will make a third accounting entry in the Tax Supported VAT account.
Cash will decrease (570), but merchandise will increase (600), this maneuver will always be repeated in compound entries, because they contain at least two accounting entries, one increases and the other decreases.
If we buy the goods in cash:
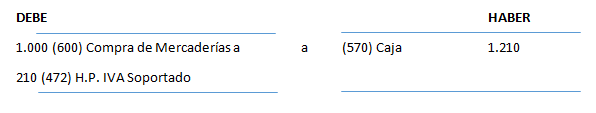
Leave a Reply