
Advance customers
The customer advance is a partial or total payment of a future acquisition of a good or service by a customer in advance.
Depending on whether they make the advance or we are the ones who do it, they will be amounts of the liability or the asset respectively. In this case we are going to study the advance we receive from the client, belonging to the group of current liabilities.
What is it for and how is it accounted for?
This advance is used to advance amounts of a future invoice, either via bank account or cash.
The accounts involved in a customer advance are:
- 57X group accounts, such as 570. Cash, or 572. Banks and credit institutions.
- Group account 47X, specifically account 477. Public treasury VAT charged.
- Group 43X account, precisely account 438. Customer advance.
- 7XX group account, especially account 700. Sale of merchandise.
The posting in a journal would be such that:
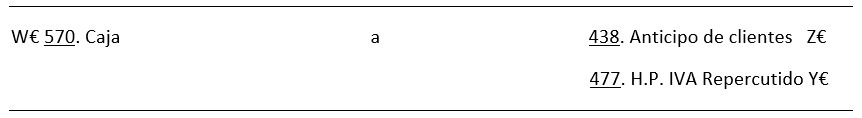
As we can see, although Z € is advanced by the client, an amount is charged to the advance itself and another to taxes, which would be X% of what is anticipated grossly.
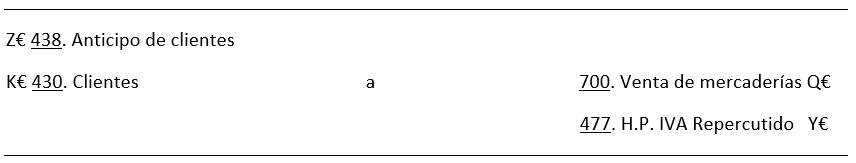
In the event that the payment is partial, the customer account must be charged for the net amount that remains to be paid, with its corresponding VAT. In addition, the merchandise sale account will be the net sum to be entered by the company.

Finally, the customer account is cleared at the time of final payment
Customer Advance Example
To make the concept easier to understand, the following example will be presented:
A client is going to advance € 1,000 via bank transfer to a carpenter for a table that he has commissioned. It is worth a total of € 2,000. Then a partial anticipation of the future invoice has been made, and the rest will be paid on the day of collection in cash.



As we can see, part of the anticipation must be charged to the tax subject to the good or service that is compulsory acquired according to the PGC. In this case we have made the simulation that the VAT tax is at 21%.
Leave a Reply