
Working capital
What is a working capital?
The working capital, working capital, working capital or revolving fund, is the capacity that a company has to face its obligations and continue to carry out their activities in the short term.
Thus, the working capital allows knowing the degree of liquidity of a company, so that it continues to operate.
How is a working capital calculated?
The working capital, then, is the difference between current assets and current liabilities. In this way:
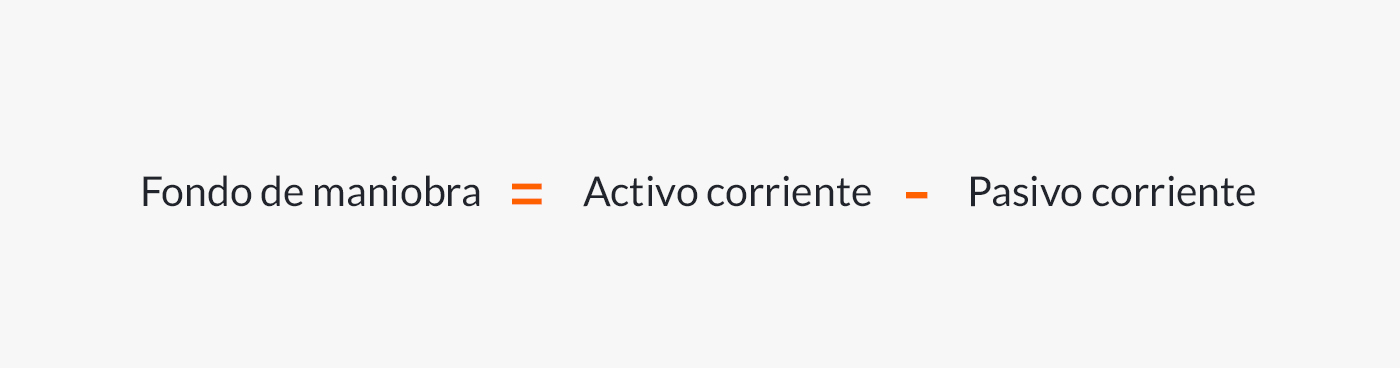
Formula to calculate the working capital.
Where:
- Current asset: it is an asset, investment, right or property of a company that can be converted into money in a period of less than or equal to one year.
- Current liabilities: are those debts that a company must cancel in a period of time less than or equal to one year.
Interpretation of working capital
The working capital can be:
- Positive: when current assets are greater than current liabilities. In this case, the company has been able to meet its short-term obligations and there is a surplus of current assets available for future commitments.
- Negative: when current assets are less than current liabilities, a situation of financial imbalance occurs, since the company's debts are not covered in the short term.
- Equal to zero: when current assets and current liabilities are equal. This is not an ideal situation, given that the company uses all its liquid assets to meet its obligations, without having a surplus for contingencies that may arise and that would place it at risk.
Example of a working capital
Let us consider the following balance sheet of CRECIENDO SA: balance sheet as of 12/31/2019.
| ACTIVE | |
|---|---|
| Current assets | 5,000,000 |
| Non-current assets | 10,000,000 |
| Total Assets | 15,000,000 |
| PASSIVE | |
|---|---|
| Current liabilities | 6,000,000 |
| Non-current liabilities | 8,000,000 |
| Total Liabilities | 14,000,000 |
| NET EQUITY | 1,000,000 |
Applying the working capital formula we have to:
- FdM = Current assets - current liabilities.
- FdM = 5,000,000 - 6,000,000.
- FdM = (1,000,000).
The FdM is negative, so the company will not be able to meet its short-term obligations. Faced with this situation, the company's financial management could adopt any of the following solutions:
- Refinance short-term debt, seeking to extend the repayment period even if it implies the payment of higher interest.
- Monetary contribution of the partners of the company to increase the balance in the treasury and comply with the pending obligations.
- Sell some non-current assets (real estate, land, automobiles) until obtaining all or part of the debt of $ 1,000,000.
| Bibliography: |
|---|
|
Leave a Reply